
Today’s European AI Consumer Market: Claude’s Retail Breakthrough vs ChatGPT
As consumers become more au fait with the AI world, the question is no longer whether they use AI, but whether they will pay and keep paying as subscription and usage-based models scale.
Consumer AI is entering its monetisation test
As investor scrutiny increases, durable consumer revenue – not just consumer adoption – is becoming the proof point for AI monetisation. Fable’s European consumer spend data captures subscriptions, top-ups and usage-based payments, and the behaviours that free-user metrics miss.
The existing evidence points to paying demand as users continue to grow despite widespread free alternatives, credible challengers, distinct monetisation methods seen through various subscription models and pricing tiers, and different customer profiles seen through demographic trends.
These signals illustrate whether consumer AI is becoming a durable paying market and how OpenAI and Anthropic are capturing it; evidence investors will watch closely for signs of any fading momentum ahead of anticipated IPOs later in 2026 and 2027.
Below we explore these signals, looking at what is driving the traction, where the monetisation opportunities are emerging, and the profile of the customers who make up these trends.
(Selected European countries shown below – for the full analysis, please get in touch)
Traction: Claude gaining ground, set to overtake ChatGPT
Claude spend per user now leads in key European markets with 2026 growth rate far outpacing ChatGPT’s, though ChatGPT still leads in the UK.
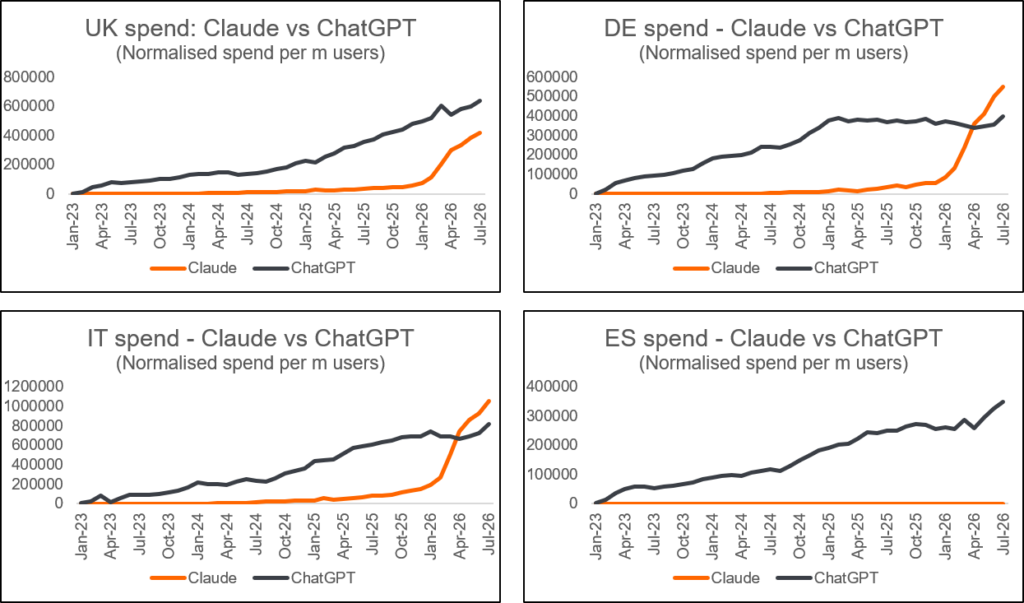
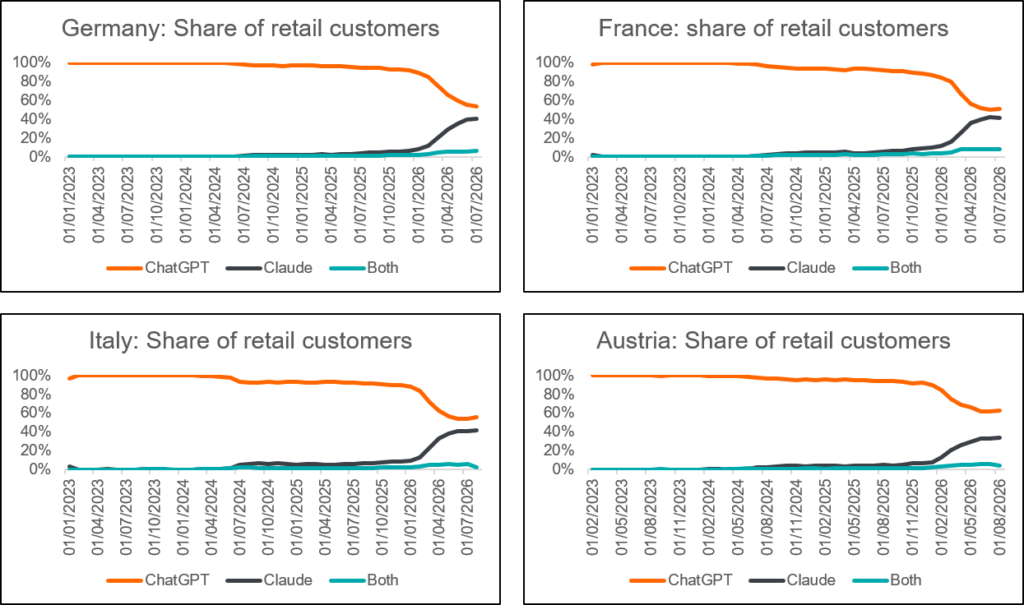
Claude has taken meaningful share of paying retail customers with its retail subscriber share rising considerably across Europe so far in 2026. At the current pace it will overtake ChatGPT to become the leading provider by the end of 2026.
Monetization: Subscription offering same same but different
ChatGPT has scaled its subscription model over the last four years to monetize its growing user base; from the original Free offering, to the Pro tier for heavy duty users, the Business and Enterprise tiers for commercial users, and, more recently, Go which offers a slight step up from the Free tier at a small price.
Specifically we see the newer Go Tier quickly gaining share as a more affordable entry plan, reaching nearly 20% of transactions in several markets and widening access alongside higher-value plans.
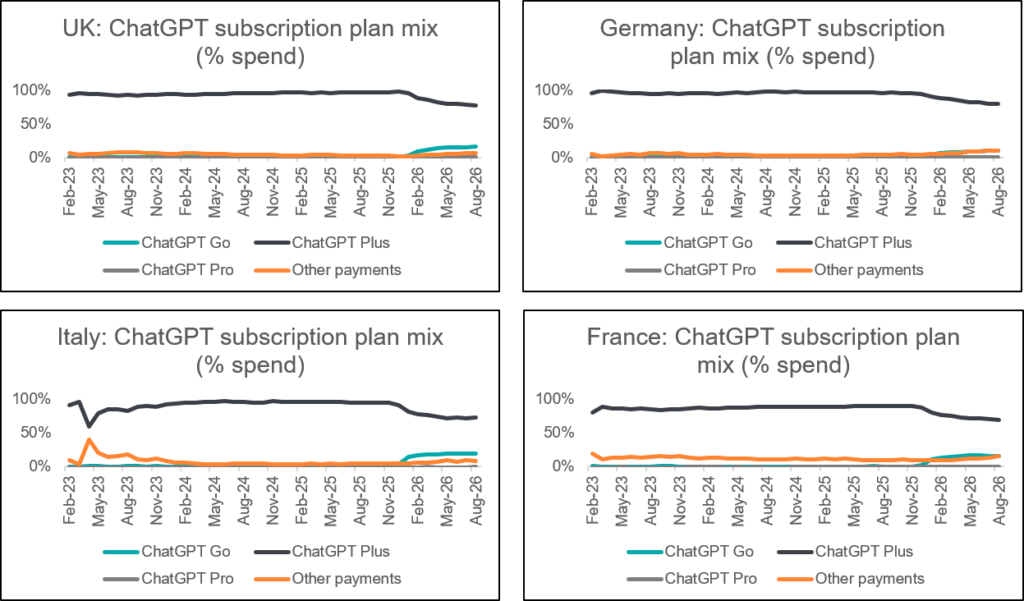
ChatGPT Plus still drives around 75% of observed revenue while more than 90% of observed OpenAI payments are subscription-related, although other payments are rising.

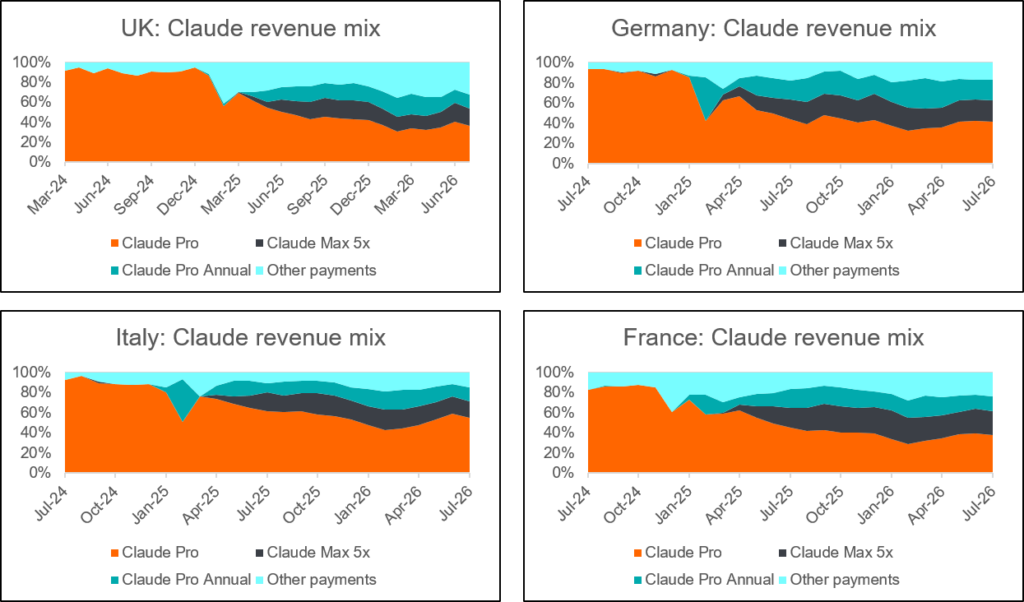
Claude’s subscription tiers are not dissimilar with the exception of Chat GPT’s Go option for which there is no Claude equivalent. However, we see a significant share of its revenue coming from usage-based top-up payments outside of users’ monthly subscription package.
We see ‘Other payments’ forming a larger share of Claude transactions than ChatGPT; subscriptions represent roughly 60–70%.
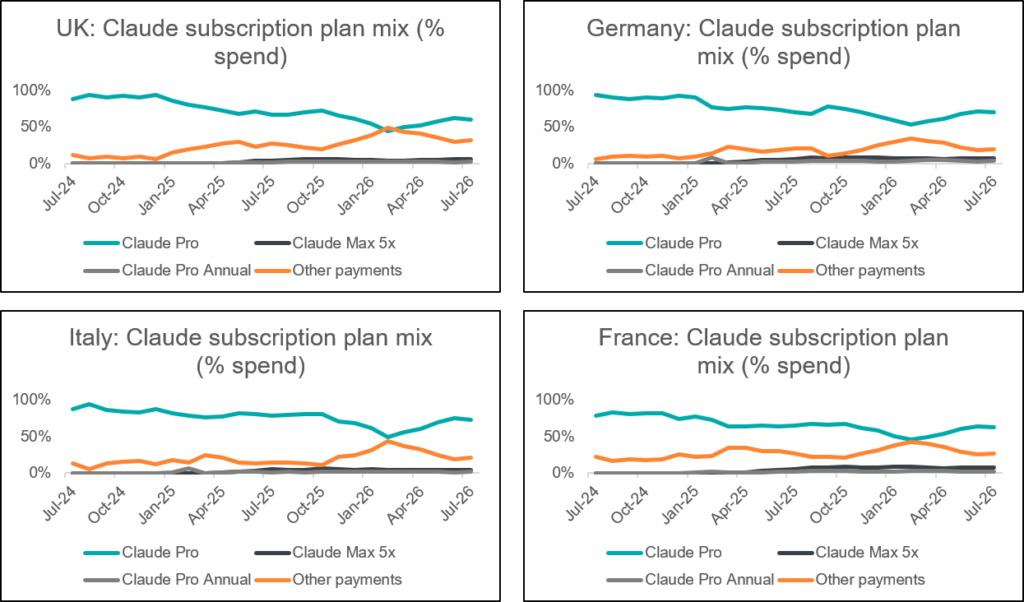
‘Other payments’ (i.e. top ups as opposed to subscription-related payments) contribute around 20–30% of consumer Claude spend. This indicates that payments made outside of typical monthly subscriptions form a material share of Anthropic’s observed revenue mix.
Profiling: Skews towards female and younger users
ChatGPT’s share of female users is rising across markets, ahead of Claude whose share is also trending higher in 2026 but remains below ChatGPT.


Claude’s user base skews younger than ChatGPT’s. Around 60% of Claude users (where age is known) are under 40 versus 53–55% for ChatGPT. Likewise, circa 25% of Claude users (where age is known) are aged 20–29 versus circa 20% for ChatGPT.


The bottom line
Durable consumer revenue – not just consumer adoption – is becoming the proof point for AI monetisation.
Fable’s European consumer spend data captures subscriptions, top-ups and usage-based payments and the behaviours that free-user metrics miss. Its granularity allows us to track spend, share, plan and revenue mix, and consumer demographics.
For more information, please get in touch: info@fabledata.com